


The ECB is changing the rules for the assets banks can use as collateral from November 30



Always see our news on Google
The Eurosystem will use the second-best available rating for numerous private assets, modify the valuation haircuts applied to collateral, and distinguish more clearly between loans that gradually repay the principal and those that repay it at the end. The new rules affect the eligibility and value of assets that banks can mobilize to obtain liquidity from central banks, without representing a change in interest rates.
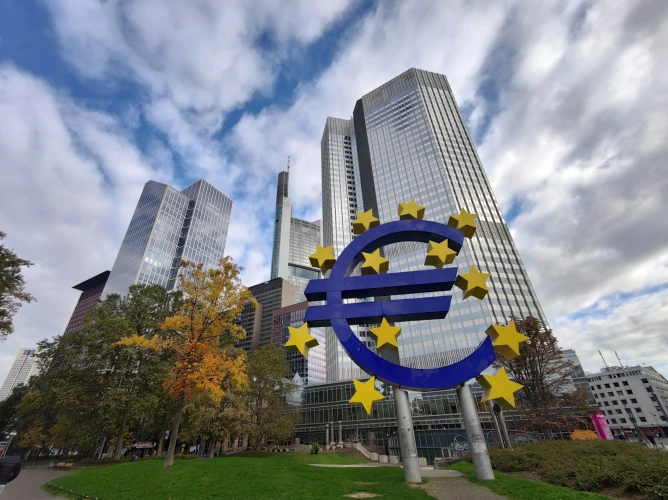
The European Central Bank has published the new rules that, from 30 November, will change how the Eurosystem assesses assets provided by banks as collateral for monetary policy operations. The changes concern the ratings used for bonds and other private-sector assets, the valuation haircuts applied to collateral, the treatment of different types of loans, and the classification of certain financial subsidiaries of non-financial companies.
In brief
1. For numerous private-sector assets, the Eurosystem will use the second-best available rating instead of the best rating to determine eligibility and the applicable haircut.
2. If there is only one eligible rating or all ratings come from the same agency, it will be adjusted downward by one notch under the new methodology.
3. The ECB is updating the haircut schedule and introducing more granular treatment for loans, including based on how the principal is repaid over the life of the loan.
4. Claims that do not fully meet the general framework but remain eligible because of public guarantees introduced during the COVID-19 period will leave the temporary framework at the end of 2026.
5. The guidelines apply from 30 November 2026 and modify the collateral mechanism for monetary policy operations. They do not represent a change in ECB interest rates.
The Eurosystem provides credit to eligible institutions only in exchange for adequate collateral. This may consist of marketable securities, such as bonds, as well as non-marketable assets, such as certain claims arising from bank loans. The rules published by the ECB establish both which assets may be accepted and what value is recognized for them when a bank mobilizes them to obtain liquidity from the central bank.
One of the most important changes concerns external ratings. For private assets for which assessments from several agencies accepted by the Eurosystem are available, the ECB will switch to using the second-best rating to determine eligibility and the applicable valuation reduction. The rule will be used for categories such as unsecured bank bonds, covered bonds, securities issued by non-financial companies, and other assets issued by the private sector.
The change also applies to certain public issuers outside the euro area. For assets issued or guaranteed by certain entities in the euro area public sector, however, the Eurosystem will retain the rule based on the best available rating. The ECB justifies the difference by pointing to the specific role of these assets in financial markets and monetary policy transmission, as well as the additional assessment mechanisms it applies to them.
The new method also changes the situation where there is only one relevant external assessment. If a single rating is available for an asset or all available assessments come from the same agency, the rating will be adjusted downward by one notch when determining eligibility and the haircut. The ECB says the measure is intended to reduce the current system’s tendency to favor the best available rating and to make greater use of information about credit risk.
A haircut is the percentage reduction applied to the value of an asset when it is accepted as collateral. If an asset with a market value of EUR 100 receives a 10% haircut, it is valued at EUR 90 for the transaction with the central bank. The higher the perceived risk, the greater the reduction may be, meaning that the bank must provide more assets for the same loan value.
The ECB is now updating the schedule of these reductions following a review of the risk-control framework. For marketable assets, the level applied will continue to depend on factors such as credit quality, remaining maturity, and coupon structure, but the new tables change the values and introduce more granular treatment for certain asset categories.
A distinct change concerns claims arising from loans. The Eurosystem will consider not only maturity, credit quality, and the type of interest rate, but also how the principal is repaid. Loans in which the principal is gradually reduced over the life of the contract are treated separately from those in which a larger proportion remains to be repaid later or at the end.
The ECB’s rationale is that the two structures involve different risks. Higher haircuts are provided for claims that do not gradually amortize the principal than for comparable loans in which the principal is repaid progressively. The difference increases in certain combinations of maturity and credit quality, meaning that the loan’s repayment structure directly influences the value recognized as collateral.
The new tables also introduce separate treatment for covered bonds used by the same institution or by an entity with which it has close links, and for securities backed by assets retained by the issuer. In these cases, the Eurosystem applies dedicated schedules that take more precise account of the risks associated with using an institution’s own assets as collateral.
Another change concerns financial subsidiaries of predominantly non-financial groups. Under certain conditions, securities issued by them will be placed in the same haircut category as the assets of the group’s non-financial companies, rather than being treated as other financial companies. These subsidiaries will be classified in Category III and may also become eligible as debtors for certain claims, while also being subject to the climate factor applied within the Eurosystem collateral framework.
The ECB is also changing the treatment of part of the measures introduced during the pandemic. Certain claims that do not meet all the conditions of the general framework but benefit from COVID-19-related public guarantees and have continued to be accepted under the temporary framework will remain eligible only until the end of 2026. The measure is part of the process through which the Eurosystem integrates some components of the temporary framework into the permanent system and removes others.
The guidelines published at the end of September codify several decisions that the Governing Council had announced separately since February 2025. The current development is their inclusion in the Eurosystem’s operational rules and the establishment of the date from which national central banks must apply them.
Guideline ECB/2026/26 amends the general documentation for implementing the Eurosystem monetary policy framework, while ECB/2026/27 amends the rules on valuation haircuts. The national central banks of the Eurosystem must take the necessary measures to apply them from 30 November 2026.
The changes may affect, for certain assets, both whether they can be accepted as collateral and the amount of credit they can support. However, they do not change the deposit facility rate, the rate on the main refinancing operations, or the marginal lending facility rate, and do not constitute a new decision on the direction of interest rates.
Latest News
21:34
21:33
21:23
21:23
21:07
See more news
NEWS ON THE SAME TOPICS



.webp)


