Parliament approves the new EU Customs Code, establishing a common authority and obligations for sellers and online platforms



Always see our news on Google
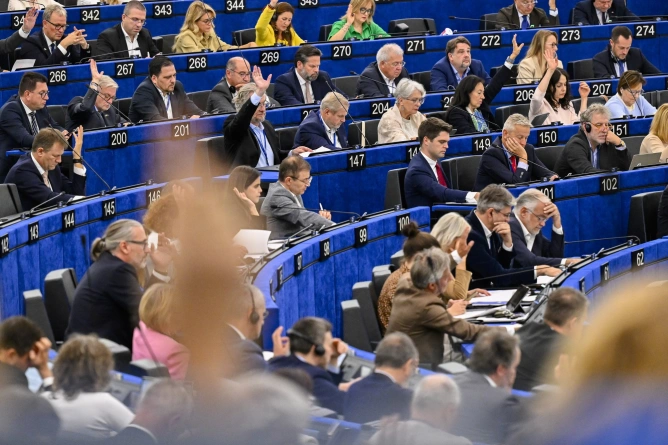
The European Parliament approved in Strasbourg the new Union Customs Code, which creates a common customs authority and changes responsibility for goods purchased online from outside the EU. The seller or platform facilitating the sale will act as the importer, with obligations regarding the information submitted to customs, payment of duties, and compliance with the requirements applicable to the products. The introduction of the new data system and related procedures will take place in stages.
In brief
Parliament completed its second reading without amendments or proposals to reject the Council’s position. The legislative procedure is complete, but the reform’s application follows a separate timetable for adoption and publication of the act.
For distance sales, the importer will be the seller or the operator facilitating the transaction, depending on the arrangement between them. This party will have to provide the necessary data, ensure payment of duties, and be responsible for the goods’ compliance with the legislation applied by customs.
The regulation introduces a European import processing fee for distance sales, calculated per item. The Commission will set the amount by means of a delegated act; this fee is separate from the temporary €3 customs duty.
Use of the European customs data system begins on 1 July 2028 for operations covered by e-commerce. Other importers, exporters, and holders of the transit procedure will be able to switch to the system from 1 March 2031, and its use becomes mandatory from 1 March 2034.
The change for e-commerce is the identification of an economic operator that assumes the importer’s obligations. The final text allows this to be the supplier of the goods or the platform facilitating the sale, depending on how the transaction is organized. Therefore, the platform is not automatically the importer for every sale made through its services.
The designated operator must submit or make available to the authorities the necessary information before release for free circulation, ensure payment of duties, and retain evidence of product compliance. It is also required to report suspected movements or unauthorized handling of goods of which it is aware. If the importer is not established in the EU, it may use an indirect customs representative established in the Union, under the conditions set out in the regulation.
The reform also introduces a processing fee intended to cover the costs of data verification, risk analysis, infrastructure, and customs controls. The amount is not included in the regulation and will be set by the Commission through a delegated act. The collection obligation will begin ten days after that act enters into force, according to the timetable established in the new code.
This fee is separate from the temporary €3 customs duty per item, applicable to low-value imports covered by the regime introduced from 1 July 2026. The two instruments have different legal bases and functions. From July 2028, the new code provides for a lower processing fee for goods sold from customs warehouses dedicated to distance sales, where the authorities can supervise the goods in batches.
The central infrastructure of the reform will be the EU Customs Data Hub, the European system through which operators will provide information for customs formalities. It will enable data processing, risk analysis, and calculation of payment obligations. The Commission is responsible for developing and operating the system and may entrust these tasks to the new European Union Customs Authority, after consulting the Member States and assessing the authority’s capacity.
The new authority will be headquartered in Lille, France, and will coordinate cooperation between customs administrations, risk analysis, and joint controls. Its mandate preserves the responsibilities of the Member States and adds operational support at European level. The authority will also contribute to monitoring the enforcement of trade sanctions and preventing their circumvention.
For companies that meet compliance and transparency criteria, the code introduces Trust and Check status. These companies will provide customs with data on the movement of goods and compliance with requirements as close to real time as possible and may receive authorization to grant release for free circulation on behalf of the authorities, under the conditions laid down by law. The existing status of authorized economic operator is retained, and the additional facilities do not remove the authorities’ right to inspect goods.
The data system timetable separates e-commerce from other flows. From 1 July 2028, importers for distance sales and users of the IOSS scheme, the one-stop shop for VAT on imports, will use the system for operations provided for by the code. For other operators, the period for choosing between customs declarations and the new system begins in March 2031 and ends in March 2034. If certain functionalities are not ready on time, the regulation requires the Commission to provide a transitional solution limited to six months.
The reform stems from the Commission’s proposal of May 2023 and the political agreement between Parliament and the Council of March 2026. At the plenary session on 16 September, the presiding officer noted that no amendments or proposals to reject the Council’s position had been submitted and announced the completion of the second reading.
The official legislative file records the signing of the act and the expectation of its publication in the Official Journal. The regulation provides for entry into force on the day following publication and, as a general rule, application after 12 months, with separate deadlines for the institutional provisions, the processing fee, and the data system. Adoption in plenary does not immediately change all formalities for companies and buyers.
Latest News
16:16
16:14
16:07
16:01
15:53
See more news
NEWS ON THE SAME TOPICS